March 25, 2025
HOPE FADING TO BUY A HOME
By Suha Beidas Zehl, CMB®, AMSP™
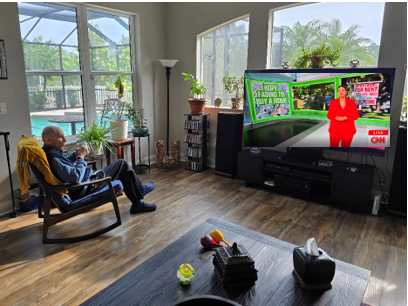
Today was no different. I brought him his morning coffee BUT something caught the corner of my eye on the screen
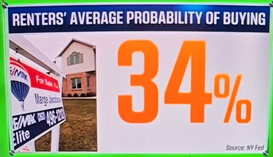
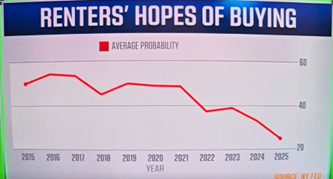
A new survey from the Federal Reserve Bank of New York show that renters are being more pessimistic about their ability to own a home in the future. Barriers to buy a home right now are VERY high and many feel these barriers are insurmountable with only 34% chance that they’ll be able to buy a home. Like EVER!
This is the lowest since the NY Fed started to ask this question a decade ago. Ten years ago, renters felt they had a 50/50 chance of buying; today it’s 1 in 3 😨
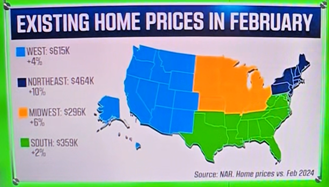
And even more troubling? It’s also a very expensive time to buy right now between home prices and high interest rates. The inventory has slightly come up, but it’s still low, but it did increase by 17% in February.
So as our industry gets ready to drop-in on DC next month for the Mortgage Bankers Association #NationalAdvocacyConference, we must make sure that we are raising the flag on this issue and that we continue to address this critical problem.
- What do we have to do to get first time home buyers into home?
✅Why does the home affordability crisis continue to grow?
✅How do we close the gap for minority home ownership?
These and many other questions need to be addressed.
This article was inspired by the report I watched this morning on CNN with my Dad; the images I used are screenshots from that segment.
Availability and affordability continue to be to be the top constraints to access to homeownership for far too many. There are programs that exist to help future homeowners, but they are fragmented at the national, state and local levels. You must be in the know, or know someone in the know, in order to leverage them. Serious change is called for. The go get’em tiger approach, while well intended, is not moving the needle.
Such a great topic for discussion - thanks for initiating the conversation! The housing affordability dilemma will definitely require a multipronged resolution. These ideas are what come to mind immediately: ⭐️ An economic environment where the consumer has more of their own money to spend 💵 - Creation of high paying private sector job opportunities 💵 - Lower taxes for more take home pay ⭐️ Address the housing supply 🏠 - Builder incentive for new construction 🏠 - Seller incentive to sell (Tax credits?) ⭐️ Reduce the cost to originate 💻 - Understand the use of technology and its opportunity to close gaps 💻 - Examine processes for efficiency gains It’s sad to me that the sentiment for homeownership is so low. It certainly does not have to be that way.
High mortgage rates, historically high home prices, and rising home insurance costs in many states. It’s not a pretty picture for the first-time homebuyer. Mike Simonsen has been working on a research paper on the affordability topic. I’m looking forward to his thoughts.
Legislation is emerging to limit investors buying single-family homes and it is gaining traction across the U.S. but, I’m not confident they will restore balance in the housing markets. There could be some positives if they Combine legislative actions with local programs and tech solutions that could help protect communities and promote more equitable housing opportunities and easier to get approved. My 23-year old son asked why we don’t have 50-year mortgages. Good question
“Barriers to buy a home right now are VERY high and many feel these barriers are insurmountable with only 34% chance that they’ll be able to buy a home.” This is concerning. Affordability is a big issue that the younger generations are facing. I have confidence that the housing industry can come together and turn this trend around, but it starts with us.
This article series opened with a pattern I kept seeing in different forms. The budget was approved.